Not too long ago, I shared an Instagram post that mentioned uninsured and underinsured motorist coverage. Then came the questions. After a few phone calls, I decided this oldie-but-goodie post was due for an update.
Here’s what cyclists should know about uninsured motorist (UM) and underinsured motorist (UIM) coverage – including how arbitration works if you and your insurance company disagree about your claim.
What is Uninsured Motorist Coverage?
Uninsured Motorist (UM) or Underinsured Motorist (UIM) coverage can be part of your auto insurance policy.
UM coverage is designed to protect you from uninsured drivers and hit-and-run collisions where the identity and insurance of the driver are unknown.
UIM coverage kicks in when you are injured by a driver who is insured, but has only limited coverage and insufficient assets to be able to cover your damages.
Do UIM Policies Cover Cyclists?
Yes, UIM policies cover cyclists.
Many cyclists don’t realize that their auto policy’s UIM coverage protects them whether or not they’re in their car.
If you’re injured as a pedestrian, cyclist, or passenger, your UIM covers you in the event of a disaster. A basic requirement for using UIM insurance is that you were not entirely at fault for the collision.
For cyclists who have been hit by a driver with little or no insurance, your own auto policy’s uninsured or underinsured motorist (UIM) coverage can save you from a bad situation becoming even worse.
The minimum liability policy for injury in California is $30,000. Visit the California DMV’s website for information on insurance requirements.
When Can I Make a UIM Claim?
An injured cyclist can only make a UIM claim if either:
1) the driver who hits them is uninsured; or,
2) they recover the full amount of the driver’s policy and it is not enough to cover damages.
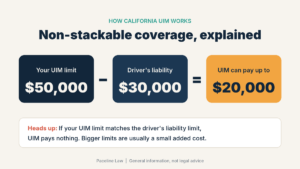
In California, UIM insurance is “non-stackable,” meaning that if you have $50,000 of coverage and the driver who hit you has $30,000, your insurance will provide up to $20,000, the difference between the driver’s policy and yours. If your UIM limit is the same as the liability limit of the responsible driver, then you won’t have any coverage. So it’s a good idea to boost your UIM protection.
How Much UIM Coverage do I Need?
In short, the answer is: Get as much coverage as you can reasonably afford.
The good news is that UIM coverage is cheap relative to liability coverage, and increasing your UIM limit substantially may result in only marginal extra cost. This is because UIM coverage is seen as lower risk: in order to use this coverage, another driver has to be at fault AND be uninsured or underinsured.
As a frequent rider and bike commuter, my opinion is that the cost is well worth it.
Can I Get UIM Insurance Without Having a Car?
Yes. Even if you do not have a car, you can still obtain UIM insurance through a “non owner operator policy.”
These policies are offered by most major insurance companies and will not only provide you protection in the event that you’re hit by an underinsured driver, but also can provide you liability coverage if you rent or borrow a car.
What is Uninsured Motorist (UM) and Under Insured Motorist (UIM) Arbitration?
UM/UIM arbitration is a private, binding legal process used to resolve disputes between an injured policyholder and their own insurance company over:
- liability; or,
- the financial value of a claim when hit by a driver with no insurance or inadequate coverage.
In California, UM/UIM disputes are required – under state statute – to be resolved by arbitration.
There are many reasons for why arbitration is preferable over traditional litigation, including:
- Speed (arbitration proceedings move more quickly than traditional court cases).
- Legal fees and court expenses are often lower.
- The proceedings and evidentiary rules involved are generally more relaxed than a traditional in-court trial.
How Does Uninsured Motorist (UM) Arbitration Work?
If an uninsured driver injures you in an accident and your UM coverage is the only viable source of recovery, you are required to resolve your dispute over liability and damages with your insurer through arbitration rather than litigation.
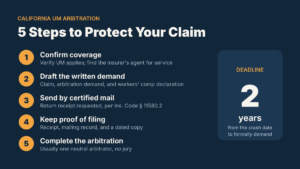
Under California law, formally demanding arbitration within two years of the accident date is one way to preserve your UM claim.
5 Steps You Need to Know for Uninsured Motorist (UM) Arbitration Proceedings
Disclaimer: This is a summary to help you better understand what you need to know and do when proceeding with UM Arbitration. For more details, check California Insurance Code § 11580 or consult a lawyer.
Step 1: Confirm Coverage and Status
Verify UM applies and identify the carrier’s agent for service.
The written arbitration demand should go to the insurer or its designated agent for service of process on file with the Department of Insurance.
Note that sending the arbitration demand to a claims office or adjuster may not satisfy the statute if the insurance carrier disputes notice.
Step 2: Draft the Written Demand
Under California Insurance Code § 11580.2(f), you must:
- State your written claim
- Demand arbitration
- Include a declaration under penalty of perjury addressing a workers’ compensation claim:
- If a workers’ compensation claim has been filed & whether it has proceeded to findings and award or settlement.
- If no workers’ compensation claim has been filed, what good cause supports moving forward with UM arbitration.
Important: If this declaration addressing a workers’ compensation claim is not included in your claim, the arbitrator will not proceed with the arbitration. This is because:
- Your physical condition has not been verified as stationary and ratable.
- The insurer can reduce a UM payment from workers’ compensation claims that you, the insured, were eligible for at the time of making an arbitration demand or would be presently eligible for.
Omitting a workers’ compensation claim will result in the arbitrator delaying the proceeding.
Step 3: Serve by Certified Mail
Under the California Insurance Code § 11580.2(i), you are required to send the arbitration demand by certified mail with a return receipt requested. This delivery method is required because the return receipt creates documented proof of having timely filed a demand.
Step 4: Preserve Proof of Filing
Retaining the receipt, a mailing record of your arbitration demand, and a dated copy is necessary to show proof that you complied with timely filing of your arbitration demand.
Step 5: Complete the Arbitration
UM arbitration, with exceptions for higher-limit cases, is conducted by a single neutral arbitrator and does not involve a jury.
The arbitrator is who determines whether you, the insured, are legally entitled to recover damages from the uninsured motorist and the amount of those damages.
If your insurer disputes coverage, that dispute would be decided by a court, not an arbitrator.
Should I Hire a Lawyer to Represent Me in UM Arbitration?
I’ll tell you what I tell everyone: should is a relative term.
Much like you do not legally need a barber to cut your hair, you do not “legally” need an attorney to represent you during arbitration proceedings. But the results you get on your own may not be what you were hoping for.
However, as a lawyer for bike people, I believe you should consider it. As you can see, these cases involve strict requirements, liability questions, and sometimes serious injuries. My advice: Speak with a bicycle injury attorney so they can help you in the process.
If You’re Injured While Cycling, Contact Paceline Law
By riding in a paceline, cyclists reduce wind drag by up to 50%. Hiring a lawyer should work the same way—reducing friction and making the legal process smoother.
If you’ve been injured in a bike or e-bike accident, I’m here to advocate for you and take on the headwinds of your legal challenges. Let’s move forward together.